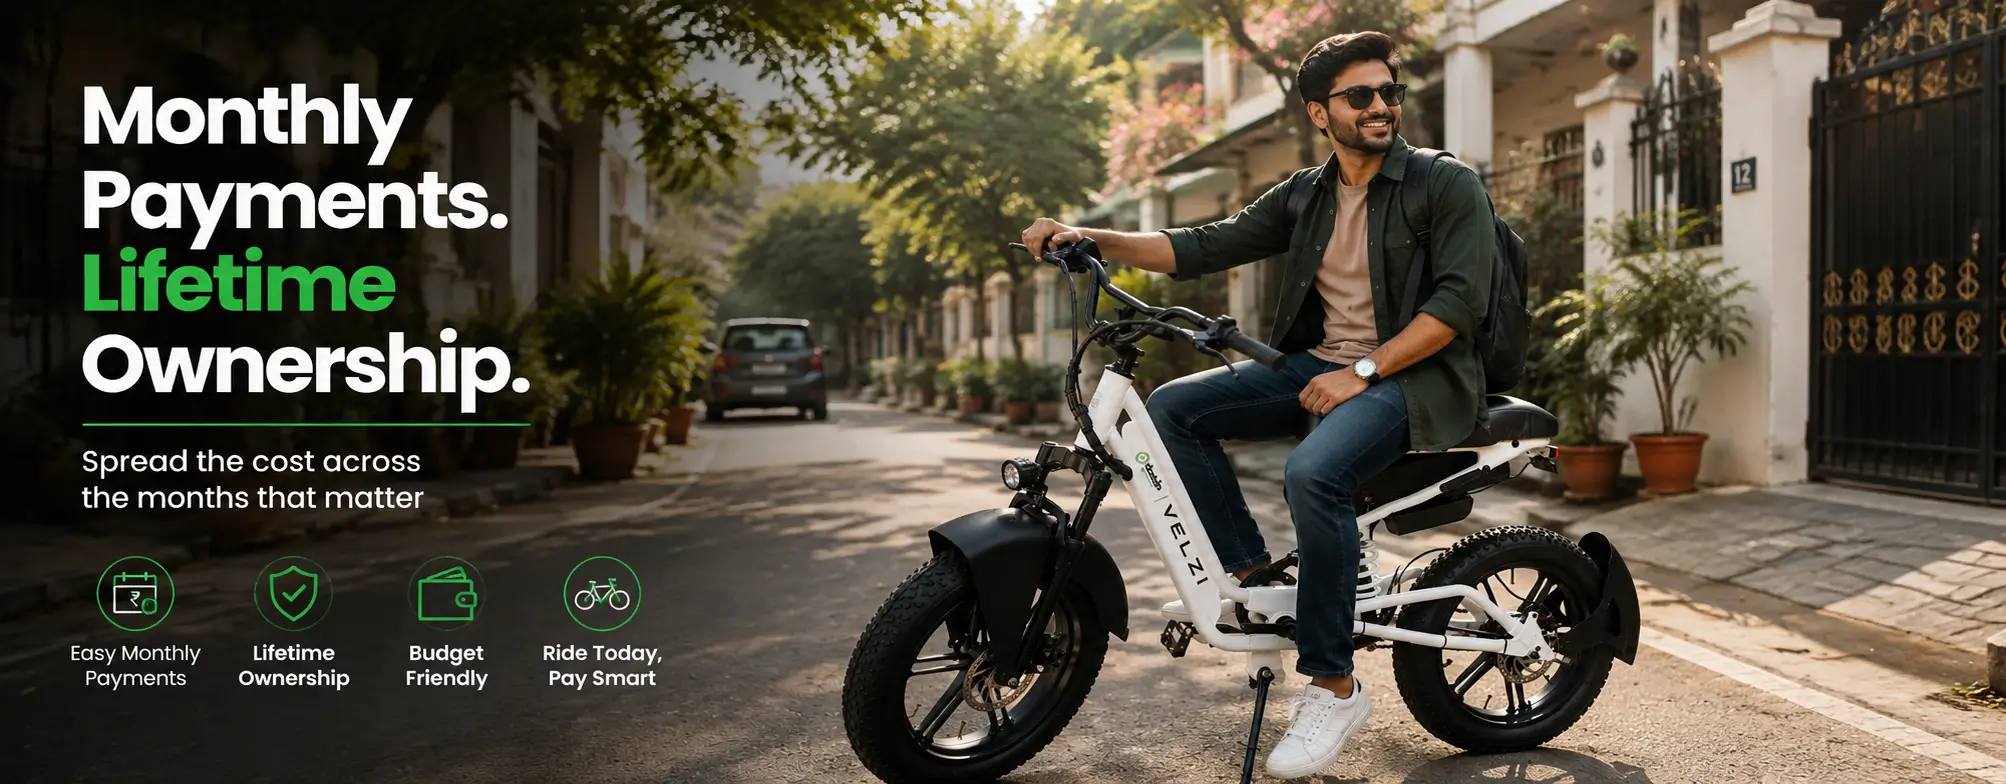
A ₹30,000–₹55,000 price tag can feel like a lot to pay upfront for an electric cycle – but almost nobody actually has to pay that way. Most Velzi buyers spread the cost over 6 to 24 months, turning it into a monthly payment that’s often lower than what they currently spend on petrol, cab rides, or auto fares.
This guide breaks down exactly how Velzi’s EMI works, what your monthly payment might look like at different tenures, and what actually changes the number on your bill – so you can decide with real figures instead of guess work.
Note: The figures below are illustrative examples to help you understand how EMI works. Actual EMI amounts depend on the exact Velzi variant, your state, and the bank/NBFC partner’s current interest rate. Confirm your final EMI on the Doddle EMI page or by speaking to the Doddle team before purchase – we’re not a bank or financial advisor, so treat this as a planning tool, not a loan offer.
Why EMI Makes More Sense Than It Sounds
Paying upfront for a vehicle – even a cycle – means locking up a lump sum you could otherwise keep as savings or use elsewhere. EMI unlocks the cycle immediately while spreading the cost alongside your existing monthly budget, the same way most people buy phones, appliances, or two-wheelers today.
The real question isn’t “EMI or no EMI” – it’s whether the monthly payment is genuinely lower than what you’re currently spending on your commute. For most daily commuters switching from petrol to a Velzi, it usually is.
Velzi Price at a Glance
Velzi is priced at ₹54,999 (MRP ₹74,999, inclusive of free pan-India doorstep delivery and GST). This is the standard price across all Velzi variants. Always confirm the current offer on the Velzi product page before finalizing your EMI plan
Illustrative EMI Table: What Your Monthly Payment Could Look Like
The table below shows how your monthly EMI changes based on the loan amount you finance, using a 14% annual interest rate and ~2% processing fee (typical for e-cycle/two-wheeler financing). Your actual EMI depends on your credit profile, chosen lender, down payment, and tenure.
For Velzi at ₹54,999, see the bottom row.
| Loan Amount | 6 Months | 12 Months | 18 Months | 24 Months |
| ₹29,999 | ~₹5,300/mo | ~₹2,750/mo | ~₹1,900/mo | ~₹1,480/mo |
| ₹39,999 | ~₹7,050/mo | ~₹3,650/mo | ~₹2,530/mo | ~₹1,970/mo |
| ₹54,999 | ~₹9,700/mo | ~₹5,020/mo | ~₹3,480/mo | ~₹2,710/mo |
How to read this table: longer tenures mean smaller monthly payments but slightly more total interest paid over the loan. Shorter tenures cost more per month but close out the loan – and the interest – faster.
These numbers assume zero down payment and an approximate 14% annual interest rate for illustration. Your actual EMI will depend on the down payment you choose, your credit profile, and the specific bank or NBFC partner Doddle connects you with.
No-Cost EMI: Pay Zero Interest with Bajaj FinServ
If the interest rates above concern you, there’s another option: Bajaj FinServ’s no-cost EMI.
With Bajaj FinServ, you pay zero interest on the financed amount. The cost of financing is covered by Bajaj, not you.
Important: Bajaj FinServ finances up to a maximum of ₹45,000. For Velzi at ₹54,999, this means you’d need to pay at least ₹9,999 as a down payment, then finance ₹45,000 over up to 8 months at zero cost. Please note that a processing fee may apply with Bajaj FinServ; confirm exact terms with the Doddle team.
How it compares:
| Financing Option | Loan Amount | Tenure Monthly | Payment | Total Interest |
| Bank EMI (14% p.a.) | ₹54,999 | 12 months | ~₹5,020 | ~₹1,740 |
| Bajaj No-Cost EMI | ₹45,000 (max) (Requires ₹9,999 down payment) | 8 months | ~₹5,625 | ₹0 |
The Bajaj option: Zero interest, but lower loan amount and shorter tenure. You pay more upfront (down payment) but close the loan faster with zero interest.
Other EMI Options: Cardless & Debit Card EMI
Beyond Bajaj no-cost EMI, you also have:
Cardless EMI (For first-time credit card users)
Available through ICICI Bank, Fibe, Early Salary
No credit card required
Interest-bearing (typical 12–16% p.a.)
Finance the full ₹54,999
Tenure: Up to 24 months
Eligibility criteria vary; check at checkout
Debit Card EMI (HDFC Debit Card Holders)
Available for HDFC debit card holders
Interest-bearing (typical 12–16% p.a.)
Finance the full ₹54,999
Tenure: Up to 24 months
Shown transparently during payment checkout
What Actually Changes Your EMI Amount
Down payment. Paying even 20–30% upfront brings your EMI down noticeably, since you’re financing a smaller principal.
Tenure. Choosing 24 months over 6 months can cut your monthly payment by more than half – useful if cash flow matters more to you than total interest paid.
Interest rate. This depends on the lending partner and your credit score. Salaried applicants with a clean repayment history typically get better rates than first-time borrowers.
Processing fees. Most NBFCs charge a one-time processing fee (commonly 1–2% of the loan amount), which is usually added to your first EMI or deducted upfront
EMI vs Paying Full Price: Which Costs You More Overall?
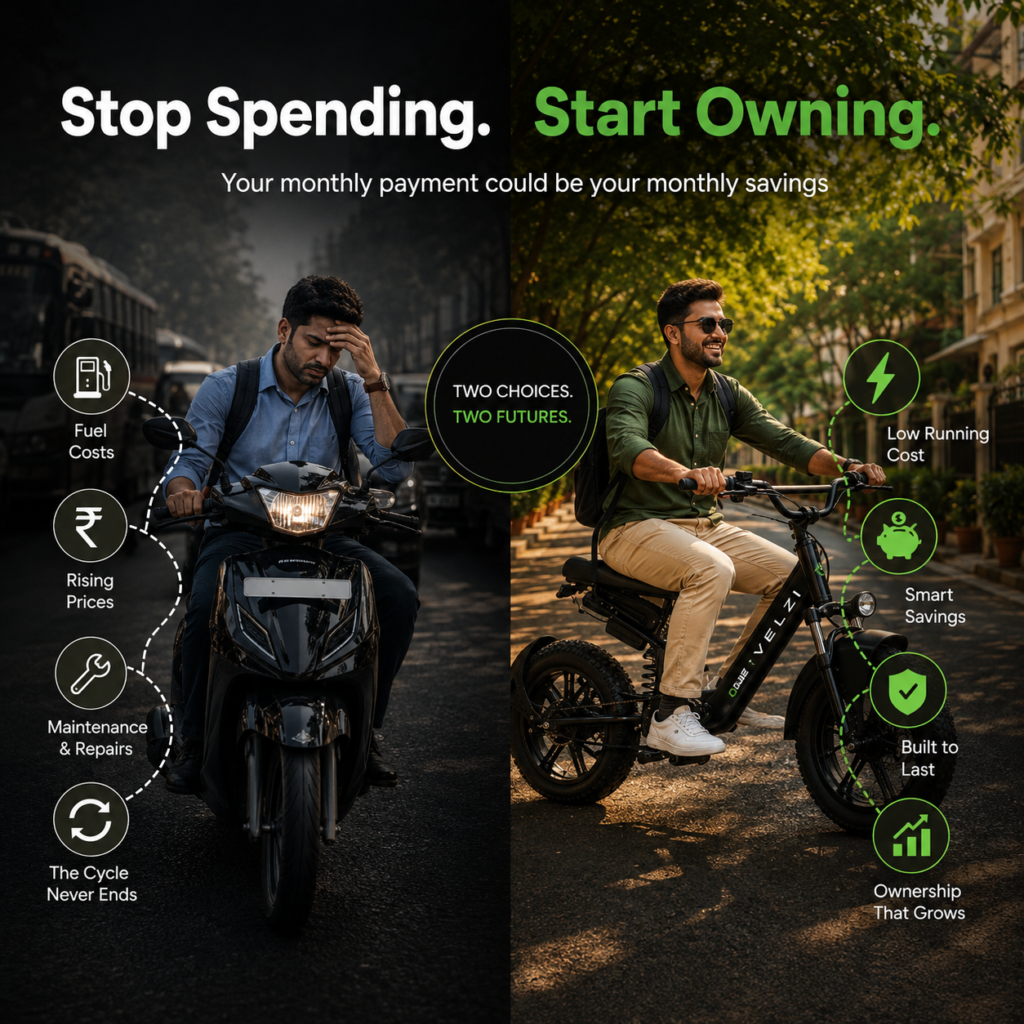
Paying the full amount upfront avoids interest entirely – so if you have the cash sitting idle anyway, it’s technically the cheaper route in total rupees. But most buyers aren’t choosing between “cash in hand” and “EMI” in a vacuum – they’re choosing between “commute now, pay over time” and “keep saving petrol money until I’ve saved enough to buy outright,” which usually means months of continued fuel spend first.
A useful way to think about it: compare your monthly EMI amount to your current monthly fuel or transport cost. If the EMI is close to or lower than what you already spend getting to work, you’re not really adding a new expense – you’re redirecting an existing one toward something you’ll own outright at the end of the tenure.
How to Apply for Velzi EMI
1. Pick your Velzi variant on the product page.
2. Visit the EMI page and share your basic details.
3. The Doddle team will call you within 24 hours to explain EMI options tailored to your profile and location:
Bajaj FinServ no-cost EMI (₹45k max, 8 months, may involve processing fee)
Bank Credit Card EMI (up to 24 months, interest-bearing)
Cardless EMI (no credit card needed, up to 24 months)
Debit Card EMI (HDFC, up to 24 months)
4. Complete verification with your chosen bank/NBFC partner.
5. Once approved, your Velzi is prepared for doorstep delivery.
Prefer to see the cycle first? You can also book a demo before deciding on financing.
Frequently Asked Questions
Is EMI available on all Velzi variants?
EMI is generally available across Velzi variants, though exact terms can vary by price point and lender. Check the EMI page or speak to the Doddle team for the latest options on your preferred variant.
Do I need a credit score to get EMI on an electric cycle?
Bank and NBFC partners typically check your credit history for EMI approval, similar to consumer financing. Applicants with an existing credit history usually get faster approval and better rates. We also offer Bajaj FinServ financing for eligible customers, which may have different eligibility criteria. Speak to the Doddle team to explore options that work for you.
What is Bajaj no-cost EMI? Is it really interest-free?
Yes. Bajaj FinServ offers no-cost EMI on eligible Velzi purchases, meaning zero interest on the financed amount. However, Bajaj finances up to a maximum of ₹45,000. For Velzi at ₹54,999, you’d need to pay at least ₹9,999 as a down payment, then finance ₹45,000 interest-free over up to 8 months (~₹5,625/month). Eligibility varies by profile. Ask the Doddle team when they call
Is there a down payment required?
This depends on the lending partner. Some offer zero-down-payment EMI, while others may require 10–30% upfront. This is confirmed at the time of application.
Can I prepay or foreclose my Velzi EMI early?
Prepayment and foreclosure terms depend entirely on your lender’s policy, not Doddle’s. We don’t restrict early repayment. Ask your lender about any prepayment charges before signing your loan agreement.
Is buying on EMI more expensive than paying full price?
Yes, technically – you pay some interest over the tenure. But if it lets you start commuting on Velzi immediately instead of waiting to save the full amount (while still spending on petrol in the meantime), the EMI route often works out more practical, even if not cheaper in absolute rupee terms.
Ready to see your exact EMI? Get your personalized Velzi EMI plan or book a free demo ride at your nearest Doddle location.
[ #VelziEMI #ElectricCycleIndia #MonthlyEMI #UrbanCommute #FatTyreCycle #ElectricVehicle #IndiaEV #CommuteSmart #BudgetFriendly #CycleLife #ElectricMobility #IndianStartup ]